You open the refrigerator and find spoiled food. A final-notice bill is buried under a stack of unopened mail. Your father has fallen twice but insists he only “tripped.” Your mother says she is taking her medication correctly, although the pill bottles and missing doses suggest otherwise.
You offer to help.
They refuse.
You suggest a cleaner, a pill organiser, a doctor’s appointment, grocery delivery, or a few hours of home care. The response is immediate:
“I’m fine. Stop treating me like a child.”
When an aging parent refuses help, the hardest part is not only the practical risk. It is the feeling of watching someone you love move toward a crisis that may be preventable—and not knowing whether you have the right to step in.
You are not powerless. But you may not have the power you wish you had.
The first step is separating several issues that can become tangled together when everyone is frightened:
Your parent’s legal right to make their own choices
The difference between a choice you dislike and genuine danger
Whether your parent may be losing the ability to make or manage important decisions
What you can realistically control
The goal is not to take over your parent’s life. It is to reduce serious risks while preserving as much dignity, independence, and trust as possible.
A parent can make choices you disagree with
An older adult does not lose the right to make decisions simply because those decisions concern their children.
If your parent is able to understand their situation and make their own choices, they may legally choose to live with some risk. They may reject recommended care, spend money in ways you consider unwise, remain in a home that feels cluttered or inconvenient, or decline services that would make life easier.
That can be very difficult to accept. You may be thinking, But I can see where this is heading.
You may be right. But predicting a bad outcome does not automatically give one adult authority over another.
It is also important not to assume that refusing help automatically means dementia, incapacity, or denial. Your parent may understand the risk perfectly well but still value independence more highly. They may fear strangers entering the home. They may worry about cost. They may feel embarrassed by changes in their abilities. They may believe that accepting one small service is the first step toward losing their home and being moved into care.
A more helpful question is not:
“How do I make my parent accept help?”
Try asking:
“Is my parent making a choice I dislike, or are they unable to understand and manage a serious risk?”
That distinction matters.
Use a danger ladder
When you are worried about a parent, every issue can feel urgent. A useful first step is to sort the situation by risk level rather than treating every concern as an emergency.
Level of concern
Examples
What to do
Immediate danger
Fire or gas hazard, severe injury, suspected overdose, stroke symptoms, no food or water, violence, parent missing or wandering, sudden severe confusion
Call 911 or the appropriate emergency service immediately
Serious and escalating risk
Repeated falls, major medication errors, unsafe driving, rapid weight loss, utilities being disconnected, financial exploitation, worsening confusion
Arrange prompt medical or professional assessment; contact Adult Protective Services where abuse, neglect, self-neglect, or exploitation may be involved
Concerning but not immediately dangerous
Clutter, missed appointments, mild forgetfulness, poor housekeeping, declining social contact
Keep a factual record, start a calm conversation, and introduce the smallest acceptable support
Difference in preference
Your parent eats differently, keeps an older home, has fewer social activities, or rejects a lifestyle you would choose
Respect the choice while keeping communication open
One situation deserves special attention: sudden confusion.
Dementia usually develops gradually. A rapid change in behaviour, alertness, orientation, or thinking can be caused by delirium or another medical problem, including infection, dehydration, medication effects, or illness. If your parent suddenly seems markedly confused, disoriented, or unlike themselves, seek urgent medical advice rather than assuming it is simply part of aging. The National Institute on Aging explains the difference between dementia and sudden confusion.
When should you contact Adult Protective Services?
Adult Protective Services, often called APS, is a state or local social-services programme for vulnerable adults experiencing abuse, neglect, self-neglect, or financial exploitation.
You may need to contact APS if:
Someone is taking or misusing your parent’s money
A caregiver is threatening, isolating, neglecting, or harming them
Your parent cannot obtain essential food, shelter, medication, or hygiene
Severe self-neglect is creating a substantial threat to their health or safety
Cognitive or physical impairment appears to prevent your parent from protecting themselves
Calling APS does not automatically mean your parent will be removed from home. The process and authority of APS vary by state, but the agency may investigate concerns, assess risk, and connect a person with services.
If there is immediate danger, call 911 rather than waiting for an APS response.
The federal Eldercare Locator, available online or by calling 1-800-677-1116, can help US families find local APS offices, Area Agencies on Aging, and other community resources. The Administration for Community Living also provides information on suspected abuse, neglect, and exploitation.
Stop arguing about “help”
To you, help may mean safer bathing, reliable medication, clean food, or fewer falls.
To your parent, help may mean losing privacy, being watched, spending money they do not have, admitting weakness, or taking the first step toward a nursing home.
If you do not understand what they are trying to protect, every practical suggestion can sound like a threat.
Instead of starting with a solution, ask:
“When I mention getting some help at home, what worries you most about it?”
Then listen without immediately correcting them.
Your parent may say:
“Strangers will go through my things.”
“I cannot afford it.”
“Once you start this, you will never leave me alone.”
“You want to put me in a home.”
“Your father made me promise I would stay here.”
“If I admit I need help, I’m no longer myself.”
The fear may be more important than the service itself.
For example, instead of saying:
“You obviously cannot manage alone anymore.”
Try:
“I know staying in this house matters to you. It matters to me too. I’m suggesting one visit from a home-safety specialist because I want to make it easier for you to stay here safely—not because I’m trying to move you.”
That is a very different conversation.
Discuss one problem at a time
Words such as stubborn, unsafe, confused, or incapable can quickly turn a conversation into an argument about identity.
Facts are usually more useful than labels.
Instead of saying:
“You cannot manage your medication.”
Try:
“On Tuesday, the morning pills were still in the organiser at dinner. On Thursday, two doses were missing. I’m worried the current system is becoming too easy to mix up. Would you be open to trying a dispenser with an alarm for two weeks?”
Instead of saying:
“You should not be driving anymore.”
Try:
“There have been two new dents on the car, and last week you entered the highway in the wrong direction before correcting. I’m worried. Could we arrange a professional driving assessment and make a backup transport plan?”
Specific observations make it harder to dismiss the issue as you “overreacting.” They also give doctors, social workers, care managers, and other professionals useful information.
Keep a dated record of significant incidents, including:
Falls
Medication errors
Unpaid bills
Getting lost
Unsafe driving
Suspicious bank withdrawals
Spoiled food
Major changes in behaviour, mood, or daily functioning
Write down what happened, not your diagnosis of why it happened.
For example:
“Mum missed two appointments this month and could not remember why she had booked them.”
This is more helpful than:
“Mum is clearly getting dementia.”
Make the first yes as small as possible
Families often start by proposing the whole solution: daily home care, moving in with an adult child, giving up driving, or moving into assisted living.
To a parent who is already afraid of losing control, that can feel like surrender.
Look instead for the smallest step that addresses the largest risk.
That could mean:
One housekeeping visit rather than “having a caregiver”
A two-week meal-delivery trial rather than taking over all meals
A pharmacist medication review instead of taking away the pill bottles
Grab bars and better lighting rather than discussing relocation
One ride to an appointment rather than demanding that they stop driving
Permission for the doctor to speak with one child rather than involving the entire family
Offer choices rather than commands.
For example:
“Would you rather try meal delivery on Mondays and Thursdays, or would you prefer someone to come in for two hours on Friday to prepare food?”
Both options address nutrition. Your parent still has a choice.
Use the word trial whenever it is honest. A temporary experiment feels much less threatening than a permanent decision.
You might say:
“Let’s try this for two weeks. If you hate it, we can talk about what did not work.”
Agree in advance about what success would look like and when you will review it.
Connect support to what matters to them
Most parents do not wake up wanting “care services.”
They may want to remain in their home, go to church, see friends, care for a pet, keep driving, avoid being a burden, maintain privacy, or continue a familiar routine.
Frame support as a tool that helps them keep doing what matters.
For example:
“The grab bars make it more likely that you can continue using your own bathroom safely.”
“A driver could get you to church when the weather is bad.”
“Automatic bill payment can help you stay in charge without worrying about lost mail.”
“A medication review may help us understand whether the dizziness is making walking harder.”
“Meal delivery could give you more energy for your gardening and social activities.”
This is not manipulation. It is explaining the benefit in the language of the person whose life is affected.
Bring in someone your parent trusts
Advice from an adult child can carry years of emotional history. Even a gentle suggestion may sound to your parent like an old family argument.
The same message may be received differently when it comes from a physician, pharmacist, clergy member, trusted neighbour, attorney, occupational therapist, or longtime friend.
Ask yourself:
“Who does my parent trust when they have to make a difficult decision?”
You could say:
“I do not want us to fight about this. Would you be willing to ask Dr. Lewis what she thinks about the falls and let us use her recommendation?”
Different problems may need different messengers:
For falls and home-safety concerns, consider an occupational therapist
For medication issues, involve the prescribing clinician or pharmacist
For money concerns, consider an elder-law attorney, trusted financial professional, or bank fraud department
For a broader assessment and care plan, consider a geriatric care manager or Area Agency on Aging
What if they will not let you speak to the doctor?
Ask your parent to sign the provider’s authorisation form and allow you to attend an appointment.
Keep your request narrow and respectful:
“I’m not asking to control your healthcare. I want permission to hear the instructions and help you carry them out.”
If your parent refuses, you can still provide the clinician with factual information. HIPAA limits what a healthcare provider may share with you, but it does not prevent you from sharing concerns with them.
The provider may not be able to reply or confirm anything about your parent’s care. But they can consider your observations.
For example:
“I understand you may not be able to reply. During the past six weeks, my mother has missed at least four medication doses, fallen twice, lost 11 pounds, and become lost while driving to a store she has used for years. The change seems to be worsening. Please consider these observations at her next appointment.”
Where a patient agrees, or in some cases does not object, HIPAA permits providers to share information relevant to a family member’s involvement in care. When a patient is incapacitated or unavailable, a provider may sometimes share limited information if professional judgment indicates it is in the patient’s best interest. The US Department of Health and Human Services explains these HIPAA rules for family and friends.
When should capacity be assessed?
It may be time to ask for a medical assessment if your parent shows a repeated pattern of being unable to understand or manage important consequences.
Being unable to explain significant financial decisions
Falling repeatedly for scams or giving large sums to strangers
Leaving dangerous appliances on
Failing to recognise an urgent medical need
Major changes in judgment, personality, memory, or daily functioning
Begin with your parent’s primary-care clinician. They may assess cognition, review medication, and look for treatable contributors such as depression, infection, dehydration, sensory loss, or medication side effects.
Capacity is not a casual family diagnosis. It may vary by decision and may change over time.
A parent might be able to make everyday choices about meals or clothing but struggle to understand a complex property transfer, major investment, or high-risk financial decision.
A diagnosis of dementia does not automatically give an adult child control over a parent’s life.
If legal authority may become necessary, speak to an elder-law attorney in your parent’s state. Laws, documents, and standards differ by jurisdiction.
Power of attorney is a plan, not a weapon
If your parent is still able to understand the decision and is willing to plan, discuss:
Advance directives
A healthcare proxy or healthcare power of attorney
A durable financial power of attorney
Estate planning documents
Emergency contacts and account information
These documents allow your parent to choose whom they trust before a crisis limits the available options.
A power of attorney does not mean that a child owns a parent’s money or controls every aspect of their life. The authority depends on the document and state law, and an agent has legal responsibilities.
Guardianship or conservatorship is a court process that can remove important rights. It should not be the first answer to family conflict or a decision you dislike.
The US Department of Justice describes guardianship as a last resort when less restrictive options are not available. Alternatives may include supported decision-making, advance directives, powers of attorney, representative-payee arrangements, carefully structured joint accounts, or limited court orders. See the Justice Department’s overview of less restrictive alternatives to guardianship.
What if driving has become unsafe?
Do not make driving a conversation about age. Focus on what you have observed: driving behaviour, vision, medication effects, physical ability, and cognitive changes.
Possible steps include:
Ask the clinician to review health and medication issues that may affect driving
Arrange an assessment with a driver-rehabilitation specialist, where available
Create alternative transportation options before asking your parent to stop driving
Set boundaries about riding with them or allowing grandchildren in the car
Learn about your state DMV’s medical-review or reporting process if serious risk continues
The National Highway Traffic Safety Administration notes that, in almost every state, a family member can report specific unsafe behaviour or medical concerns to the DMV, although confidentiality rules vary. Its guidance for families of older drivers explains the process.
Taking car keys secretly can create new problems. Your parent may report the car stolen, find another vehicle to drive, or become isolated without a transport plan.
In an immediate emergency, prevent the trip if you can do so safely and call the appropriate authorities. For an ongoing concern, use medical, legal, and DMV processes rather than trying to manage the problem alone indefinitely.
Be clear about what you control
You may not be able to control whether a capable parent accepts help.
You can control:
The help you are willing and able to offer
The amount of time or money you can provide
Whether you take part in something unsafe
Whether your children ride with an unsafe driver
What conditions apply if your parent lives in your home
Whether you report suspected abuse, exploitation, or serious self-neglect
Whether you call emergency services during immediate danger
How you communicate with siblings and professionals
A boundary is not a punishment or threat. It is a clear statement about what you will do.
For example:
“I respect that this is your decision. I cannot continue filling the pill organiser if the doses are changed afterwards. I can arrange a pharmacist review and an automatic dispenser, or we can ask the doctor for another plan.”
Or:
“I cannot let the children ride with you after the two recent driving incidents. I will drive you to their activities, and I will help arrange a driving assessment.”
Do not promise care that you cannot sustain. In a crisis, it is easy to say, “I will do everything.” Over time, that can lead to exhaustion, resentment, and burnout.
Reliable help with honest limits is more loving than a promise that eventually collapses.
Do not let sibling conflict take over
Families often respond differently to an aging parent’s decline.
One sibling may see clear danger. Another may think everyone is overreacting. A sibling who lives far away may criticise the person dealing with daily emergencies. Old family roles can return quickly.
Try to create a shared factual record. Hold a short conversation focused on:
What has actually happened
Which risk is most urgent
What your parent wants
What each person can realistically contribute
Which professional assessment may be needed
When the family will review the plan
Avoid voting to “take over” a competent parent. The aim is to coordinate support, not stage a family coup.
A 30-day plan
Today
Decide whether this is an emergency, a serious escalating risk, or a difference in preference
Write down the three incidents that concern you most, including dates and facts
Identify the single risk most likely to lead to serious harm
Choose a calm moment for one conversation, rather than raising the issue during an argument or crisis
During the next seven days
Ask your parent what they fear losing if they accept help
Offer two small, reversible options that address one specific risk
Ask for permission to attend a medical appointment or communicate with the clinician
Agree with siblings on facts, responsibilities, and limits
During the next 30 days
Arrange an appropriate medical, medication, driving, or home-safety assessment
Test one practical support and review whether it worked
Discuss advance directives and powers of attorney while your parent can still choose whom they trust
Create an emergency contact sheet with medication, diagnoses, clinicians, and key contacts, with your parent involved where possible
Decide what circumstances would require APS, DMV, legal, or emergency action
Love does not give you total control
You can say the right thing, offer practical support, and still hear “no.”
You can see the risks clearly and still be unable to prevent every bad outcome. That does not mean you failed your parent.
Your responsibility is not to remove every risk from another adult’s life. It is to notice what is happening, communicate respectfully, offer workable support, act when danger becomes serious, and refuse to participate in situations that are unsafe or impossible for you.
Sometimes progress does not look like your parent saying, “You were right.”
Sometimes progress is:
Permission to attend one medical appointment
One grab bar in the bathroom
One bill set to automatic payment
One medication review
One trusted neighbour having a spare key
One small service accepted on a trial basis
Respecting autonomy does not mean abandoning your parent. Protecting safety does not require humiliating them.
The difficult work lies between those two extremes. That is where small, specific, and patient actions can make the greatest difference.
Your action points
Triage the danger: Call emergency services for immediate threats. Use APS when you suspect abuse, neglect, self-neglect, or exploitation.
Use facts, not labels: Record specific incidents and their consequences.
Ask what help threatens: Independence, privacy, money, identity, or the ability to remain at home.
Start small: Try one reversible step that reduces the greatest risk while preserving choice.
Use a trusted messenger: Involve a clinician, pharmacist, occupational therapist, care manager, attorney, clergy member, or aging-services specialist where appropriate.
Plan early: Discuss advance directives and powers of attorney while your parent can still choose whom they trust.
Set honest boundaries: Be clear about your money, time, home, vehicle, children, and participation in unsafe situations.
Protect yourself too: Share responsibility, use caregiver support, and do not commit to more care than you can safely provide.
This article provides general educational information for families. Medical, privacy, driving, protective-services, and decision-making laws vary by state and individual circumstances. Seek emergency assistance for immediate danger, and obtain advice from qualified local professionals for personal medical or legal decisions.
Being laid off after 50 is not just a career setback. It can shake your confidence, your finances, and your sense of identity all at once.
You may have spent decades building experience, earning trust, solving difficult problems, and becoming the person others turned to when things went wrong. Then, suddenly, a restructuring, merger, budget cut, contract loss, or management change makes your role disappear.
It is understandable if one question keeps coming back:
Who is going to hire me now?
The answer is not always simple. Finding a new job after 50 can require a different approach from the one that worked earlier in your career. Age bias does exist, even if employers rarely state it openly. They may quietly wonder whether you will be too expensive, comfortable with new technology, willing to report to a younger manager, or likely to leave when a better offer appears.
But you do not need to pretend to be younger, erase your experience, or accept that you must start again at the bottom.
Your job is to show that your experience is relevant now. You need to make it clear that you understand current problems, can work with modern tools, and can deliver results that matter to an employer today.
A layoff is painful, but it is not a verdict on the rest of your working life.
First, separate the layoff from your worth
A layoff is usually a business decision. It can result from a merger, a lost customer, a new executive team, automation, a weak quarter, or a change in company strategy. Even if performance was part of the decision, one employer’s decision does not define the value of your entire career.
The emotional side is still real.
Many people feel embarrassed after losing a job. They withdraw from former colleagues because they do not want to explain what happened. They spend hours alone revising their résumé, then read every unanswered application as proof that they are too old or no longer wanted.
Try not to make permanent career decisions during the first few days of shock.
You are allowed to feel angry, frightened, disappointed, or exhausted. Tell the people closest to you what has happened. Then create a manageable routine. One useful call, one benefits application, one updated résumé section, or one conversation with a former colleague is enough to begin restoring a sense of control.
You do not need to solve your future in a week. You need to protect your options and start moving again.
What to do in the first 72 hours
Your first priority is not finding your next job immediately. It is protecting your financial, legal, and healthcare options before you make decisions under pressure.
1. Do not sign a severance agreement in a panic
Ask for the complete severance agreement and benefits information in writing. Read it carefully before signing anything.
Check the following:
Severance amount and payment schedule
Final salary, unpaid commission, bonuses, and unused paid leave
The date your health insurance ends
COBRA information and costs
Retirement-plan, pension, stock, deferred-compensation, or equity treatment
Non-compete, non-solicitation, confidentiality, and non-disparagement clauses
Reference wording and rehire-status language
Any release of legal claims
If you are 40 or older and the agreement asks you to waive claims under the Age Discrimination in Employment Act, specific federal requirements may apply. In many individual cases, employees must be given at least 21 days to consider a waiver, followed by seven days to revoke it after signing. Certain group termination programmes may require at least 45 days for consideration.
The agreement should also tell you in writing that you should consult an attorney. These rules depend on the circumstances, so consider asking an employment lawyer to review the document before you sign. The EEOC’s guidance on severance waivers and discrimination claims explains the key requirements.
Do not assume the first offer is non-negotiable. Depending on your role and the circumstances, you may be able to ask for:
Additional severance
Continued employer-paid health coverage
Prorated bonus treatment
Outplacement support
Neutral reference language
Changes to an overly broad non-compete or non-solicitation restriction
You may not get everything you ask for, but asking a sensible question is different from accepting the first document in front of you because you are afraid.
2. Apply for unemployment benefits quickly
Unemployment benefits are not charity and they are not a personal failure. They are part of the employment system and exist to provide temporary income after qualifying job loss.
Apply as soon as you can. Each state has its own rules and procedures, and remote or multi-state work can make the process more complicated. In many situations, you apply in the state where you worked. The official USAGov unemployment-benefits page can direct you to the correct state agency.
Keep copies of:
Your layoff notice
Pay records
Severance documents
Employment agreement
Job-search activity
Any correspondence with your former employer
Unemployment income may not replace your full salary, but it can give you the breathing room needed to make better decisions rather than accepting the first unsuitable role out of panic.
3. Protect your health insurance
Before you start comparing job offers, find out the exact date your employer-sponsored health coverage ends.
Then compare your main options:
Joining a spouse’s employer health plan, if one is available
Continuing your previous employer’s coverage through COBRA
Purchasing coverage through the Marketplace
COBRA may allow you to keep your existing doctors and benefits, but it can be expensive because you generally pay the full premium yourself. Losing job-based insurance usually qualifies you for a Marketplace Special Enrollment Period.
According to HealthCare.gov, you normally have 60 days after losing coverage to enrol in a Marketplace plan. The amount of financial help available can depend on your expected household income for the year and the size of your family.
Do not simply accept the first COBRA bill without comparing alternatives.
4. Do not rush to cash out your 401(k)
After a layoff, retirement savings can suddenly look like emergency cash. Before withdrawing money, pause long enough to understand the consequences.
Depending on your plan and account balance, your options may include:
Sometimes retirement money really is needed to prevent a more serious crisis. The point is not to protect a retirement account while ignoring food, rent, or medical care. The point is to avoid making an irreversible decision before you understand the alternatives.
If possible, speak to a qualified tax adviser or financial professional before taking money out.
Do not try to look younger
One common reaction to being laid off after 50 is trying to hide age at all costs.
People remove so much history from their résumé that their seniority and credibility disappear. They apply for junior roles they do not really want. They use language that sounds unlike them in an attempt to appear younger or more fashionable.
That approach often backfires.
You do not need to look 35. You need to look like a 52-, 57-, or 61-year-old professional who understands today’s work, tools, and business problems.
Employers do not hire “years of experience” on their own. They hire people who can achieve a result.
They want someone who can:
Restore an underperforming operation
Retain a major customer
Improve safety, quality, or compliance
Deliver a delayed project
Reduce costs without damaging service
Develop managers and stabilise a team
Prevent an expensive problem before it gets worse
For example, this résumé statement is weak:
Seasoned executive with 28 years of extensive experience across multiple functions.
It says very little about the value you provide.
This is stronger:
Operations leader who improves delivery performance, develops frontline managers, and restores underperforming sites. Reduced late orders from 18% to 6% across three facilities while improving safety performance.
The second version does not hide seniority. It makes seniority useful.
Build a three-lane job search
Do not place all your hopes on one type of position. A better approach is to run three job searches at the same time.
This reduces pressure and gives you more ways to generate income, stay current, and find the right longer-term opportunity.
Lane 1: Your direct-successor role
These are jobs closest to your previous level, function, and industry.
If you were a regional operations director, for example, this lane includes regional operations, business-unit leadership, plant leadership, or similar roles in the same sector.
This route is usually the most direct way to preserve seniority and compensation. It may also take longer because there are fewer senior openings and hiring processes can be slow.
A weak response does not necessarily mean your experience is no longer valued. It may simply mean the market is smaller and more selective.
Lane 2: An adjacent problem you can solve
Look beyond job titles and focus on the problems you know how to solve.
An operations leader may have a strong case for roles in:
Supplier performance
Business transformation
Programme leadership
Continuous improvement
Integration after mergers or acquisitions
Operational risk
Customer delivery recovery
A banking executive may move into risk, compliance, regulatory operations, fintech partnerships, or governance.
This is not starting over. It is applying existing judgment in a different setting.
Lane 3: Bridge work
A bridge role can include:
Contract work
Consulting
Interim leadership
Project-based roles
Fractional executive work
Teaching or training
Work with smaller organisations that need broader leadership
A bridge role is not automatically a step backwards. It becomes a problem only if you take it without a purpose.
A good bridge role should provide at least two of the following:
Meaningful income
Recent accomplishments
New professional contacts
Exposure to current tools or a new sector
A credible route to longer-term work
Imagine David, a fictional 55-year-old manufacturing manager. He may not immediately find another local plant-manager job. Instead, he accepts a six-month supplier-recovery contract.
That work gives him current results to discuss in interviews, access to leaders at several companies, and income while he continues searching for the right permanent role. He has changed his employment format, not erased his career.
Rebuild your résumé around proof
Your résumé should answer three questions in its first third:
What problem do you solve?
At what level can you solve it?
What evidence shows that you can do it?
Use a specific headline
Avoid vague phrases such as “seeking new opportunities” or “experienced professional.”
Use a recognisable function and a clear value proposition instead:
Healthcare Operations Director | Multi-Site Performance | Cost, Quality and Team Development
That instantly tells the reader what you do and where you create value.
Replace the objective with a value summary
Write three or four lines that connect your strongest capabilities to the sort of role you want.
Do not try to summarise your whole career. Your goal is to help the recruiter or hiring manager understand your relevance quickly.
Give recent experience the most space
Your last 10 to 15 years should usually receive the most detail, especially where it relates directly to your target roles.
Earlier roles can be condensed under an “Additional Experience” heading. This keeps the résumé focused without pretending those earlier years did not exist.
You can also leave off graduation dates if they are not relevant or required. Do not, however, falsify dates, qualifications, or employment history.
Turn responsibilities into results
“Managed a team of 35” describes your job.
“Rebuilt a 35-person service team and increased first-call resolution from 71% to 86%” shows what changed because of your work.
Look for evidence in areas such as:
Revenue won, protected, or recovered
Costs reduced or avoided
Time saved
Safety or quality improvements
Risks prevented or controlled
Customers retained
People developed, promoted, or retained
Projects delivered or recovered
Use numbers where you can support them. If the numbers are confidential, use credible percentages, ranges, or descriptions without disclosing sensitive company information.
The US Department of Labor’s CareerOneStop résumé guidance similarly recommends focusing on relevant accomplishments rather than presenting a generic work history.
Make LinkedIn show that you are current
Recruiters often look at LinkedIn before deciding whether to contact you. Your profile should support your résumé, but it does not need to repeat it word for word.
Update the following:
A current, professional, approachable headshot
A headline that describes your target value, not only your former title
An About section written in plain first-person language
Five to ten skills aligned with current job descriptions
Short, achievement-based descriptions for recent roles
Some recent activity that demonstrates engagement with your field
You do not need to become a LinkedIn influencer. One thoughtful comment on an important industry development is more useful than posting generic motivational messages every day.
If you recently completed a project, learned a relevant platform, helped an organisation informally, or completed a useful course, include it. Employers look for signals that you are active and current. Those signals come from your examples, your language, and your visible engagement—not from pretending to be a different age.
Use your network for information first
After 50, your network can be one of your strongest advantages. The difficult part is often emotional. Asking for help may feel like admitting defeat.
Try to think of it differently. Reconnecting with people who know your work is not asking them to rescue you. It is part of a professional job search.
Instead of opening with, “Do you know of any jobs?”, ask for market insight.
You could say:
I was affected by the recent restructuring at Northstar. I’m now focusing on operations leadership roles where I can improve multi-site delivery and develop managers. I’m speaking with people whose judgment I trust to understand where companies are investing and which problems are getting executive attention. Would you be open to a 20-minute conversation next week?
At the end of the call, ask:
Based on what I’ve described, who are one or two people you think I should speak with next?
This creates a more useful conversation. You may gain information, better language for your search, introductions, and eventually job leads.
Make four contact lists:
Former managers and senior colleagues
Former peers and direct reports
Customers, suppliers, and professional advisers
Trade associations, alumni, and community contacts
Do not overlook former direct reports. Careers move in every direction. Someone who reported to you several years ago may now work at exactly the organisation that needs your experience.
Address the concerns employers may not say aloud
Employers may never say, “We think you are too old.” Instead, their concerns may show up in other ways:
Will this person expect more money than we can afford?
Will they leave if something better comes along?
Can they use our systems and technology?
Will they accept direction from a younger manager?
Do they want to do the work, or only supervise others?
Can they adapt to a faster-moving or less structured environment?
These are concerns you can address directly, calmly, and with evidence.
If compensation is the concern
You might say:
I’m interested in the scope of the role, the team, and the problems I would be trusted to solve. I’m not trying to recreate every detail of my previous compensation. If we find a strong fit, I’m confident we can have a practical conversation about the overall package.
Do not volunteer to take a major pay cut before you understand the role, the salary range, and the full package. Flexibility is useful; desperation weakens your position.
If they think you are overqualified
You could say:
I understand the question. I’m interested because the role keeps me close to the operational work I enjoy and gives me a clear problem to own. I’m not viewing it as a temporary stop. The scope appeals to me for specific reasons.
Then explain those reasons. Employers cannot read your motivation. If you want a role for good reasons, say so clearly.
If your prospective manager is younger
You could say:
I have worked with leaders at different career stages and from different backgrounds. What matters to me is clarity, trust, and accountability. My role is to help my manager and the team succeed, not compete over who has been working longer.
This shows maturity without sounding defensive.
If technology is the concern
Do not simply say you are a quick learner. Give an example.
In my last role, I helped move the forecasting process from spreadsheets to Power BI dashboards. I was not the technical developer, but I defined the operating measures, learned the workflow, and helped three regional teams use the new system consistently.
Specific evidence is much more persuasive than reassurance.
Refresh one skill, not your entire identity
After a layoff, it can feel safer to sign up for another degree, certification, or long course of study. Training can be useful, but endless preparation can also become a way to delay the job search.
You do not need to solve every possible skills gap before applying.
Instead, collect 20 realistic job descriptions for the roles you want. Look for repeated skills, tools, and keywords. Then divide them into three groups:
Skills you already have but describe using outdated language
Skills you can demonstrate through equivalent experience
Genuine gaps that are likely to prevent interviews
Focus on the most important gap first. Choose the smallest credible way to close it:
A short course
An industry certification
A volunteer project
A portfolio example
A supervised assignment
A practical software demonstration
The CareerOneStop Skills Matcher can also help you identify how your current skills transfer to adjacent occupations.
You are not trying to become a beginner in everything. You are looking for one or two visible signals that make it easier for employers to connect your experience with the current market.
Apply selectively and track what happens
Online applications still matter, but they should not be the whole strategy.
For every serious opportunity:
Identify the three most important outcomes in the job description.
Adjust your résumé summary and strongest achievement bullets to reflect those outcomes truthfully.
Use the employer’s language where it accurately describes your own experience.
Find a relevant person who may be able to provide context, such as a former colleague, recruiter, department leader, or mutual connection.
Follow up once with a short, useful message.
Track the role, contact, date, next action, and result in a simple spreadsheet.
Then look at the pattern.
What is happening?
What may need attention?
Applications but no interviews
Positioning, résumé, target roles, or keywords
First interviews but no progress
Examples, interview answers, fit, or unspoken concerns
Final interviews but no offer
References, compensation, executive presence, or stronger competition
Conversations but no opportunities
Network message may be too vague or unfocused
Do not respond to disappointing results simply by sending more applications. Work out where the process is breaking down, then improve that stage.
A job search can feel emotional and personal. Tracking the evidence helps you make practical adjustments instead of reacting from anxiety.
Know when age discrimination may matter
Federal law does not guarantee that an older worker will be hired, and it does not make every unfair decision illegal. It does, however, prohibit covered employers from discriminating against people aged 40 or older because of age in hiring, layoffs, compensation, and other employment decisions.
The Age Discrimination in Employment Act generally applies to private employers with at least 20 employees, as well as certain other entities. State laws may offer additional protections. The EEOC’s age-discrimination overview explains the federal framework.
If you notice warning signs, document the facts. These may include:
Explicit comments about age
Inconsistent explanations for a layoff or hiring decision
A clear pattern in who was selected for redundancy
A job advertisement that unlawfully states an age preference
A sudden shift from positive reviews to vague criticism shortly before termination
Keep lawful copies of relevant documents, emails, performance reviews, agreements, and notes. Do not remove confidential company information you are not entitled to keep.
Deadlines can be short. In many cases, an EEOC charge must be filed within 180 calendar days, although the deadline can sometimes extend to 300 days under applicable state law. Federal employees follow different rules. Review the EEOC filing-time guidance promptly and seek legal advice based on your own circumstances.
A practical 30-day reset
Days 1–3: Protect yourself
Obtain your termination, severance, insurance, and benefits documents
Put every important deadline on your calendar
Apply for unemployment benefits
Compare health-insurance options
Avoid an automatic 401(k) withdrawal
Seek legal or financial advice if the agreement or your finances require it
Days 4–7: Define your target
Write down five business problems you solve well
Choose your three job-search lanes
Collect 20 realistic job descriptions
Set a compensation floor based on household needs, not panic or pride
Create a weekly routine that includes exercise, family time, and at least one day with limited job-search activity
Week 2: Rebuild your evidence
Rewrite the top third of your résumé
Create six achievement stories using situation, action, and measurable result
Update your LinkedIn headline, About section, and recent experience
Prepare a one-page portfolio or case-study sheet if it suits your field
Ask three trusted people whether your materials clearly show your current value
Week 3: Reopen your network
Contact five people each working day
Schedule at least three market-intelligence conversations
Join one relevant industry, alumni, or professional event
Contact a local American Job Center for free employment and training assistance
Ask useful contacts for one or two further introductions
Week 4: Test and adjust
Submit a small number of well-matched applications
Practise answers to questions about salary, overqualification, technology, and younger managers
Review which job-search lane is creating the strongest response
Close one genuine skills gap through a visible course, project, or certification
Update your résumé and message based on evidence, not fear
You are not starting over
Starting over would mean that nothing you learned in your career still matters.
That is not what is happening.
You are translating experience gained in one setting into value that another employer can recognise. Some things may not survive the transition: a familiar company name, a senior title, a large team, a generous benefits package, or a particular compensation structure. Losing those things can be painful, and it is reasonable to grieve them.
But your judgment, professional relationships, ability to spot risk, pattern recognition, resilience, and capacity to prevent costly mistakes still belong to you.
The right job search does not apologise for those strengths. It makes them visible.
You do not need every employer to understand your value. You need a focused group of employers, clients, recruiters, and professional contacts to understand what you can solve now.
Your action points for today
Before the end of today:
Put every severance, benefits, and health-insurance deadline on your calendar
File for unemployment through your state’s official website
Write one sentence describing the business problem you solve, rather than simply naming your former title
Create three job-search lanes: direct-successor roles, adjacent opportunities, and bridge work
Send one market-intelligence message to someone who knows the quality of your work
Replace one responsibility on your résumé with a measurable result
Choose a specific time tomorrow to continue your search—and stop working on it for tonight when that time arrives
Losing a job after 50 is a serious disruption. It can affect your income, confidence, and sense of direction at the same time.
It is not proof that your useful working life is over.
Protect your options. Make your value clear. Widen the paths through which your next opportunity can reach you. You do not have to solve everything today. Take the next practical step, then take the one after that.
If you are 50 and have little—or nothing—saved for retirement, it is easy to feel that you are too late.
Maybe your money went toward raising children, getting through a divorce, supporting family members, medical bills, or simply keeping the household afloat. Perhaps you worked for employers that never offered a retirement plan. Reading another article about what you “should” have saved by now is unlikely to help.
The useful question is not whether you made perfect decisions in the past. It is: what can you change from today?
A recent discussion among people in their 50s on Reddit reflected this reality. Many were not looking for abstract advice about building a seven-figure portfolio. They wanted to know how ordinary people retire after setbacks, interruptions, and years of competing financial priorities.
The answers were mixed, but some themes were consistent. People improved their position by paying down debt, lowering housing costs, working longer where possible, making better use of Social Security, and accepting that retirement might look simpler than they once expected. Others had seen reasonable plans unravel because of illness, caregiving, divorce, or job loss.
That does not mean everything will work out automatically. It means your future retirement is about more than the current balance in an investment account.
At 50, you cannot change the years that have passed, future market returns, or government policy. You can still influence:
How much you save from now on
How long you can remain employed
When you claim Social Security
How much debt you carry into retirement
Your housing and transport costs
The financial support you provide to other adults
Here is a practical 30-day starting plan.
Days 1–3: Work out your real monthly cost
Do not start by asking how you will save $1 million.
Start with a more immediate question: What does it cost to run my life each month?
Review the last three months of bank and credit-card statements. Put every expense into four categories:
Essentials: housing, groceries, utilities, transport, insurance, and healthcare
Debt payments
Financial support for adult children, parents, or other relatives
Optional spending
Then calculate your bare-bones monthly expenses: the amount required to keep your household operating safely, without extras.
For example, perhaps you take home $5,000 per month and believe you have only $300 left after spending $4,700. A closer review may show $250 in subscriptions you barely use, $300 in frequent takeaway meals, and $400 going each month to an adult child with no clear end date.
This is not an argument for removing every small pleasure from your life. It is about making deliberate decisions. At this stage, every recurring expense deserves to be weighed against your future financial security.
Days 4–7: Check your Social Security estimate
Create a free my Social Security account at SSA.gov and review both your earnings record and projected retirement benefits.
Your Social Security benefit is based in part on your highest 35 years of earnings. If your record contains missing or incorrect years, address that now rather than discovering the problem close to retirement.
For people born in 1960 or later, full retirement age is 67. You can claim benefits from age 62, but the monthly payment will be permanently lower. Waiting beyond full retirement age increases the payment until age 70. The Social Security Administration’s calculators can help you compare possible claiming ages.
For illustration, your estimate might look like this:
Claiming age
Estimated monthly benefit
62
$1,700
67
$2,400
70
$2,980
Those figures are examples, not a prediction of your own benefit. The point is that the age at which you claim can make a substantial difference.
Now compare your projected benefit with your essential expenses. If you expect to need $3,500 per month and Social Security may provide $2,400, you are looking at a potential shortfall of $1,100 per month.
That shortfall is the number your savings, work decisions, debt reduction, and housing choices need to address.
Days 8–10: Build a small emergency fund
When there is no cash reserve, every car repair, medical bill, or disruption to income risks becoming new debt.
Open a separate savings account and set an initial target of $1,000 to $2,000. In time, you may want several months of essential expenses in cash. But the first goal should be realistic enough that you actually reach it.
Set up an automatic transfer on payday, even if it is only $50.
A starter emergency fund will not solve every financial problem. It can, however, stop a $600 car repair from turning into years of credit-card interest.
Days 11–14: Get the full employer match
If you have access to a 401(k), ask your benefits department:
How much do I need to contribute to receive the full employer match?
When do employer contributions become fully vested?
What investment options are available?
Is there a low-cost target-date fund?
Suppose your employer matches 50 cents for every dollar you contribute, up to 6% of your salary. If you earn $70,000 and contribute 6%, you put in $4,200 a year and your employer adds another $2,100.
That employer contribution is part of your compensation. If you contribute nothing, you leave it behind.
Your first target is to contribute enough to receive the full match. If that is not affordable immediately, start at a lower percentage and arrange automatic increases—perhaps 1% every three months.
Days 15–18: Make a debt-payoff plan
List every debt, including:
Current balance
Interest rate
Minimum monthly payment
Expected payoff date
Keep making the minimum payment on every account. Then direct any extra cash toward the highest-interest debt first, particularly credit cards.
Be cautious about withdrawing money from a 401(k) to eliminate debt. Taxes, possible penalties, and the loss of future investment growth can make an early withdrawal much more expensive than it first appears.
The objective is not necessarily to pay off a low-rate mortgage as quickly as possible. It is to prevent high-interest credit cards, personal loans, and vehicle payments from consuming income that you will later need in retirement.
If your debt feels unmanageable, speak with a reputable nonprofit credit-counselling organisation or a bankruptcy attorney before taking money from protected retirement accounts.
Days 19–21: Use the age-50 contribution limits
Reaching 50 gives you access to higher retirement-plan contribution limits.
For 2026, employees may generally contribute up to $24,500 to most 401(k), 403(b), and governmental 457 plans. People aged 50 and above may contribute an additional $8,000, if their plan permits it.
The 2026 IRA contribution limit is $7,500, with an additional $1,100 catch-up contribution available to people aged 50 and older. Income levels and workplace retirement-plan participation can affect Roth IRA eligibility and the deductibility of traditional IRA contributions, so check the current guidance from the IRS.
These figures are limits, not targets. You do not need to contribute the maximum amount before you can make meaningful progress.
Consider a 50-year-old earning $72,000 who starts by contributing $360 a month to a 401(k). If her employer adds $180, a total of $540 goes into the account each month.
Over the next two years, she clears her credit-card debt and increases her own contribution to $900 per month. With the employer match, $1,080 then goes into the account each month.
If that amount earned a hypothetical average annual return of 6% over 17 years, it could grow to roughly $380,000. Actual outcomes will depend on investment performance, fees, taxes, and market conditions. Still, the example makes an important point: starting from zero at 50 does not mean reaching 67 with nothing.
Days 22–25: Focus on the big costs
Cutting small expenses can help, but your largest recurring costs will have the greatest effect on retirement.
Ask yourself:
Will my mortgage be paid off before retirement?
Could I eventually downsize or move to a less expensive area?
Am I maintaining more house than I need?
Can I keep my current vehicle for longer?
Am I supporting adult children at the expense of my retirement?
Could I live comfortably in a lower-cost city or state?
A person who needs $3,000 per month in retirement faces a very different challenge from someone who needs $6,000.
The solution does not have to be an extreme lifestyle. It may mean reaching retirement with manageable housing, a paid-off vehicle, fewer monthly obligations, and clearer limits around financial support for family.
Days 26–28: Protect your ability to earn
Working longer is not a personal failure. For many people, it is one of the strongest available retirement strategies.
An additional year of work can provide:
Another year of retirement contributions
More time for investments to grow
One fewer year that must be funded from savings
A potentially higher Social Security benefit
Continued access to employer health insurance
Healthcare is particularly important. Medicare generally begins at 65, so the cost and availability of coverage may affect when retirement is realistically possible.
Do not assume you can remain in your present role indefinitely. Update your résumé. Build skills that remain valuable in your industry. Learn how AI and technology may affect your work. Maintain relationships beyond your present employer.
The goal is not to work forever. It is to preserve your options before a layoff, health issue, or employer decision takes them away.
Days 29–30: Put it on one page
At the end of the month, write a one-page recovery plan containing:
Your essential monthly expenses
Your estimated Social Security benefit
Your emergency-fund target
Your employer-match percentage
Your monthly retirement contribution
Your debt-payoff order
One major expense you will reduce
Your preferred retirement age
One action that will strengthen your employability
Then consider meeting with a qualified financial planner who clearly explains how they are paid and whether they act as a fiduciary at all times.
Bring your actual numbers. Do not simply ask, “Am I doomed?”
Ask a more useful question:
“Given my income, expected Social Security benefit, expenses, debt, and remaining working years, which changes would have the greatest effect on my retirement security?”
Your next steps
During the next 30 days:
Calculate your bare-bones monthly expenses.
Check your Social Security earnings record and benefit estimates.
Build your first $1,000 in emergency savings.
Contribute enough to receive the full employer match.
List every debt and prioritise repayment.
Increase retirement contributions automatically when possible.
Set reasonable limits on support for other adults.
Review housing, transport, and healthcare costs.
Take one practical step to protect your earning ability.
Seek professional advice based on your own circumstances.
You cannot recover the years already gone. You can stop another year from passing without a plan.
Your first contribution may feel small. Make it anyway. At this point, the most important step is not finding the perfect investment. It is ending the period in which nothing is being saved at all.
I wrote this article for general educational purposes only and is not individual financial, investment, tax, or legal advice.
Feeling lost, restless, or like your best years are somehow behind you? You’re not alone — and you’re not finished. Here’s how real people over 50 rediscovered their sense of purpose and built the most meaningful chapter of their lives.
There’s a quiet crisis that rarely makes headlines. It doesn’t hit all at once. It creeps in slowly — on a Sunday afternoon when the house feels too still, on a Monday morning when the thought of another week at the same desk feels unbearable, or the moment your last child drives away to college and you realise you’ve been so focused on everyone else’s story that you’ve lost the plot of your own.
If you’re over 50 and wondering “What is my purpose in life?” — welcome to one of the most important questions you will ever ask yourself. And here’s the truth that doesn’t get said enough: finding purpose after 50 is not only possible — for many people, it’s when life finally makes sense.
Research from Stanford University’s Center on Longevity shows that people in their 50s and 60s often report higher levels of emotional wellbeing than younger adults. The wisdom you’ve accumulated, the clarity that comes from lived experience, and the freedom that this season of life offers can make your post-50 years your most purposeful yet. But only if you’re intentional about it.
Here are five proven strategies — backed by real-life stories — to help you rediscover your ikigai (the Japanese concept meaning “reason for being”) and start living with deep, authentic purpose.
1. Reconnect With the Person You Were Before Life Got in the Way
One of the most powerful tools for finding purpose after 50 is looking backward before you look forward. Between the ages of 15 and 25, most of us had passions, dreams, and instincts that were alive and unfiltered. Then life happened — mortgages, careers, relationships, responsibilities. Those early interests didn’t die; they just got buried.
Rediscovering your pre-adult passions is one of the most reliable pathways to purpose in midlife and beyond.
Real-Life Story: David’s Second Life as a Musician
David Chen spent 27 years as a corporate accountant in Singapore. At 53, following a routine health scare, he found himself going through old boxes in his garage. Among the clutter was a dusty guitar he’d played obsessively as a teenager. On impulse, he signed up for adult guitar lessons. Within a year, he was playing in a local acoustic group, performing at community events, and teaching weekend music workshops for seniors. “I didn’t find a new purpose,” David says. “I found my original purpose. It had been waiting for me the whole time.”
Action Step: Make a list of everything you loved doing between ages 12 and 22, before anyone told you it wasn’t practical. What patterns do you see? These clues are more valuable than any career assessment tool.
2. Redefine Success on Your Own Terms
One of the most common reasons people over 50 feel purposeless is that they’ve been chasing someone else’s definition of a meaningful life — a definition built around titles, salaries, status, and external validation. After decades of playing by those rules, many arrive at 50 having “won” the game only to find it was never the game they actually wanted to play.
Finding purpose in life after 50 often starts with the courageous act of rewriting the rulebook.
This isn’t about rejecting ambition. It’s about trading shallow ambition for deep ambition — pursuing things that matter to you, not to a performance review.
Real-Life Story: Margaret’s Exit from the Corner Office
Margaret Osei was a Vice President at a major UK insurance firm when she walked away at 56. From the outside, her life looked like the definition of success. From the inside, she felt hollow. “I had spent 30 years building a career I thought I wanted. At 56, I finally admitted I had been performing success rather than living it.” Margaret spent six months volunteering with a micro-finance NGO in Ghana before launching a financial literacy programme for young women in underserved communities. Today, she describes herself as more energised, more engaged, and more alive than at any point in her corporate career. Her income is lower. Her sense of purpose is off the charts.
Action Step: Write down three things you chase out of obligation or social expectation versus three things that, when you do them, make you lose track of time entirely. Your purpose almost certainly lives closer to the second list.
3. Use your hard-won expertise to Serve Others
Here’s something that people searching for “meaning and purpose after 50” often miss: you are sitting on a goldmine. Everything you know — the skills, the hard lessons, the industry knowledge, the life wisdom — is precisely what someone younger desperately needs. Shifting from accumulation to contribution is one of the most powerful transitions a person in midlife can make.
Mentoring, coaching, teaching, writing, or consulting are not second-choice careers. They are high-impact pathways that leverage everything you’ve built while giving your life a sense of legacy and meaning that few things can match.
Real-Life Story: Robert’s Unexpected Second Career as a Coach
Robert Fernandez spent 25 years as a structural engineer before retiring early at 58. He assumed retirement would feel like freedom. Instead, it felt like irrelevance. On the suggestion of a friend, he began informally mentoring junior engineers at a local firm. The response was overwhelming. Within 18 months, Robert had formalised his approach, earned a professional coaching certification, and launched a small consultancy helping mid-career engineers navigate career transitions. “I had spent my whole career building things out of steel and concrete,” he says. “Now I build people. It’s the most satisfying work I’ve ever done.”
Action Step: List the top five things you know deeply — skills, industries, hard-earned insights, or lived experiences. Then ask: Who needs this knowledge and can’t easily access it? That intersection is often where purpose hides.
4. Build New Social Ecosystems Around Shared Values
Research consistently links a strong sense of purpose in midlife and later life to social connection and community belonging. Yet many people over 50 find that their social world has quietly contracted — children have left, colleagues have retired, and old friendships have faded with geography and changed circumstances.
Rebuilding a vibrant social life isn’t just good for your happiness. It is essential for a purposeful life. The connections you build around shared values, causes, and interests will often become the very context in which your new purpose takes root and flourishes.
Real-Life Story: Susan and the Running Club That Changed Her Life
At 54, Susan Park was recently divorced, her two children were living abroad, and she described herself as “profoundly, almost embarrassingly lonely.” On a whim, she joined a local running group for beginners over 50. She had never run before. Within months, the group had become her core community. The shared vulnerability of learning something new as older adults created bonds quickly. Two years later, Susan now co-organises charity runs that raise funds for women’s shelters, has built deep friendships, and says the combination of physical challenge, shared mission, and community belonging gave her a sense of purpose she had never felt even during her busiest career years.
Action Step: Identify one community, club, cause, or class aligned with something you genuinely value — not just something convenient. Show up consistently for 90 days. Purpose rarely arrives in a flash of inspiration; it grows slowly in the soil of committed relationships.
5. Embrace Reinvention as a Lifelong Practice, Not a One-Time Event
Perhaps the most liberating shift you can make in your 50s is this: stop looking forthepurpose and start living purposefully. Purpose is not a destination you arrive at. It is a practice, a direction, a way of engaging with life that evolves as you do.
Many people delay their reinvention because they’re waiting for a grand vision or a guaranteed outcome. But purpose rarely works like that. It reveals itself through action, through experimentation, through saying yes to things that scare you a little and no to things that slowly drain the life from you.
This is especially important for those experiencing what psychologists call the midlife transition — a period of deep questioning about identity, legacy, and meaning that is not a crisis to be survived but an invitation to be answered.
Real-Life Story: James and the Blog That Became a Movement
James Adeyemi had worked in corporate human resources for 28 years when, at 57, he began writing a blog about navigating workplace stress in your 50s. He had no plan, no audience, and no clear sense of where it was going. He simply started writing honestly about his own experience. Within two years, his blog had over 40,000 monthly readers. He had been invited to speak at three major conferences, signed a book deal, and built an online community of thousands of people who shared his belief that midlife is the beginning of something, not the beginning of the end. “I didn’t plan this purpose,” James says. “I acted my way into it.”
Action Step: Choose one thing you’ve been “thinking about doing” for more than six months and commit to starting it — imperfectly and immediately. Give it 90 days of genuine effort. Purposeful living is built on the decisions you make before you feel ready.
The Bigger Picture: Why Finding Purpose After 50 Matters More Than Ever
The science is unambiguous. A strong sense of purpose in midlife and later life is associated with better physical health, lower rates of depression and anxiety, stronger cognitive function, and even greater longevity. A landmark study published in JAMA Network Open found that people with a higher sense of purpose had significantly lower mortality risk. This is not a soft, feel-good concept. Living with purpose is one of the most powerful health interventions available to people over 50.
You are not too old. You are not too late. You are not running out of time. In many ways, you are only now equipped with everything you need to live your most meaningful life.
Summary: Your Action Plan for Finding Purpose After 50
Here’s a quick recap of the five strategies and the action steps to get started today:
1. Reconnect with your early passions. List everything you loved doing between ages 12 and 22. Look for patterns — your original purpose is often still waiting there.
2. Redefine success on your own terms. Distinguish between what you chase out of obligation and what genuinely energises you. Build your life closer to the second list.
3. Leverage your expertise to serve others. Identify your deepest knowledge and skills, then find the people who need them most. Mentoring, coaching, and teaching are among the most purpose-rich activities available to you.
4. Build community around shared values. Join one group, cause, or class aligned with something you genuinely care about. Show up for 90 days and let belonging do its quiet, powerful work.
5. Start before you’re ready. Pick one thing you’ve been postponing and begin it imperfectly and immediately. Purpose is not found — it is built, one action at a time.
Your 50s, 60s, and beyond are not the epilogue of your story. They may well be its most important chapters. The question is not whether you have time. The question is whether you’re willing to begin.
What step will you take this week?
Did this post resonate with you? Share it with a friend who needs to hear it, and drop a comment below — I’d love to know what purpose looks like for you at this stage of life.
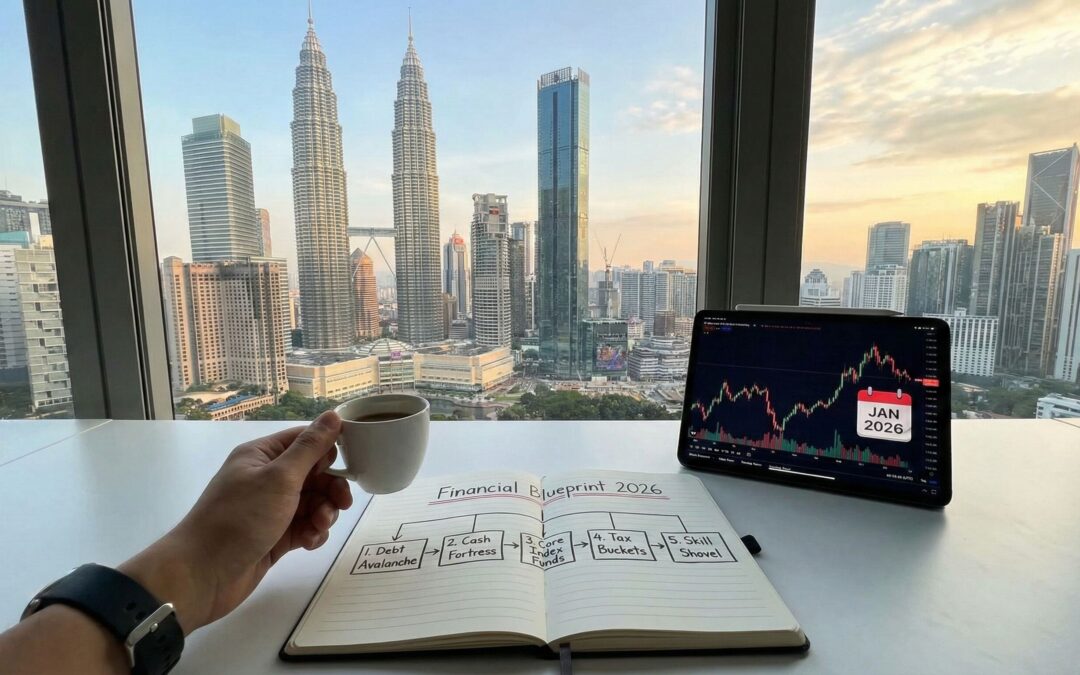
I was sitting here this morning, looking out at the skyline of Kuala Lumpur, thinking about how quickly time moves. It’s early 2026. If you’re like me, you probably spent the last week of December reflecting on where you are and where you want to go.
Maybe you’re starting today with exactly zero dollars in your investment account. Maybe there’s a little bit of debt hanging over your head like a low-hanging cloud, and your job pays the bills but doesn’t quite leave enough for the life you’ve been dreaming of. The news is full of talk about AI taking over roles, fluctuating interest rates, and a housing market that feels increasingly out of reach.
It’s easy to feel frozen. It’s easy to assume the game is rigged and decide not even to pick up the controller. But I want to share something that really shifted my perspective recently. If I had to start from absolute zero right now—knowing what I know about compounding, market cycles, and the engineering behind a solid financial plan—I wouldn’t panic. In fact, 2026 might be one of the cleanest entry points we’ve seen in a decade, provided you know how to ignore the noise.
This isn’t about getting rich by Tuesday. This is a mathematical roadmap—a “peer review” for your finances—designed to take you to your first $100,000 and beyond. Let’s walk through the five phases of this strategy together.
Phase 1: Breaking the Negative Compounding Trap
Before we can build a house, we have to clear the site. In engineering, we call this a structural integrity check. In finance, it’s about identifying the “invisible anchor” dragging you backward: high-interest debt.
I see it so often—people asking which tech ETF or crypto coin they should buy while they’re sitting on credit card debt at 20% or 24% interest. There’s a pervasive myth that you can out-invest your bad habits. But let’s look at the math, because while feelings can lie, numbers don’t.
If you have $5,000 in consumer debt at 24% interest and you only make the minimum payments, you’ll end up paying back nearly double that amount over the next decade. Meanwhile, the stock market historically returns about 10% before inflation. Mathematically, paying off that debt is a guaranteed 24% return. You simply cannot find that in the market without taking risks that could wipe you out.
This is what I call the Negative Compounding Trap. Until you fix the leak in the bucket, the water will never stay in.
The Protocol:
I use the Avalanche Method. List every liability from the highest interest rate to the lowest. Ignore the balance size; only care about the rate. Throw every spare dollar at that top-tier debt while paying minimums on the rest. Sell what you don’t need, downgrade those “zombie” subscriptions, and treat this like a hair-on-fire emergency.
Once that high-interest debt is gone, don’t celebrate by buying a new watch or upgrading your car. Take that entire monthly payment and pivot.
Phase 2: Building Your Cash Fortress
The next trap is one that catches 90% of new investors. You pay off the debt, you feel great, and you immediately dump your next paycheck into the S&P 500. Then, life happens. Your car needs a major repair, or you face an unexpected medical bill. If your money is tied up in stocks and the market is down that month, you’re forced to sell at a loss just to survive.
You’ve just destroyed your compounding.
Conventional wisdom says “cash is trash” because inflation eats its value. But in the early stages of wealth building, cash isn’t an investment—it is insurance.
I call this the Cash Fortress. When you have 3 to 6 months of expenses sitting in a High Yield Savings Account (HYSA), you walk differently. You negotiate differently at work because you aren’t desperate. This buffer creates a physiological gap between a market crash and your response. It allows you to look at a “red” market as a sale rather than a catastrophe.
The Protocol:
Calculate your bare-bones survival number—rent, food, utilities, and transport. Multiply it by three. That is your target. Automate a transfer every payday into a boring, liquid account. Once it’s full, pretend it doesn’t exist. It’s for survival only.
Phase 3: The Engine – Core and Satellite Investing
Now that the foundation is solid and the fortress is built, we look at the stock market. But here’s the thing: we need concentration to build and diversification to preserve.
In 2026, the temptation to use “AI stock pickers” is everywhere. Apps promise “alpha” by picking the next big winner. But let’s look at the data. Over a 15-year period, more than 90% of professional active fund managers fail to beat a simple index like the S&P 500. If the pros with Bloomberg terminals can’t do it, the odds of us doing it in our spare time are statistically zero.
The myth is that you need to be smart enough to pick the winners. The reality is you just need to be smart enough not to pick the losers.
The Core-Satellite Protocol:
The Core (90%): Put the vast majority of your cash into low-cost, broad-market index funds (like VTI or VOO). This is automated. You never touch it. It’s boring, and it should feel like watching paint dry.
The Satellite (10%): Allow yourself a small “gambling” sliver. If you want to pick a specific tech stock or crypto, do it here. If it goes to zero, your life is fine. If it goes to the moon, great. This scratches the itch without blowing up the plan.
Phase 4: The Tax Shield (Your Financial Rulebook)
You can pick the perfect funds and still lose 30% of your wealth to taxes. I’ve learned to look at the tax code not as a burden, but as a rulebook for wealth.
If you’re investing in a standard brokerage account, you’re volunteering to give the government a massive slice of your gains. We need to fill the tax-advantaged buckets first.
For my friends in the US, this means the Waterfall Method:
401k to the Employer Match: This is an immediate 100% return. Never leave free money on the table.
Max out a Roth IRA: Tax-free growth and tax-free withdrawals.
HSA (Health Savings Account): The “triple tax advantage.”
Back to the 401k: Fill it to the cap.
Even here in Malaysia, the principle remains: maximize your EPF (KWSP) contributions and look into Private Retirement Schemes (PRS) for that tax relief. Every dollar you shield from tax drag is a dollar that compounds for you, not the IRS or LHDN.
Phase 5: Expanding the Shovel (The Income Pivot)
Finally, we have to talk about the “latte effect” myth. Sure, wasteful spending is bad, but you cannot budget your way to wealth on a stagnant salary. Inflation in 2026 makes the cost of living a moving target.
Defense prevents you from losing, but offense is how you win.
If I’m starting at zero, I have to shift from “How do I save $5?” to “How do I earn $5,000?” This requires a Skill Audit. What is the one skill that, if you mastered it, would make you undeniable in your field? Maybe it’s data analysis, specialized project management, or a technical certification in your industry.
Investing in your primary income engine is the highest-leverage move you can make. Increasing your “shovel” (your income) makes every other step work 10 times faster.
A Final Reflection
Starting from zero in 2026 isn’t about finding a shortcut. It’s about building a system that respects the laws of math and human psychology.
Kill the debt (The Avalanche).
Protect the plan (The Fortress).
Be average (Index Funds).
Shelter the gains (Tax Buckets).
Increase the shovel (Skill Mastery).
It isn’t sexy. It isn’t a get-rich-quick scheme. It is a get-wealthy-for-sure scheme.
I’ve run these numbers a thousand ways in my own “peer reviews,” and they always point back to these fundamentals. But personal finance is, well, personal. I’d love to hear your take—are you focusing on debt payoff this year, or are you in the “fortress-building” phase?
Let’s keep reflecting, keep growing, and keep building.